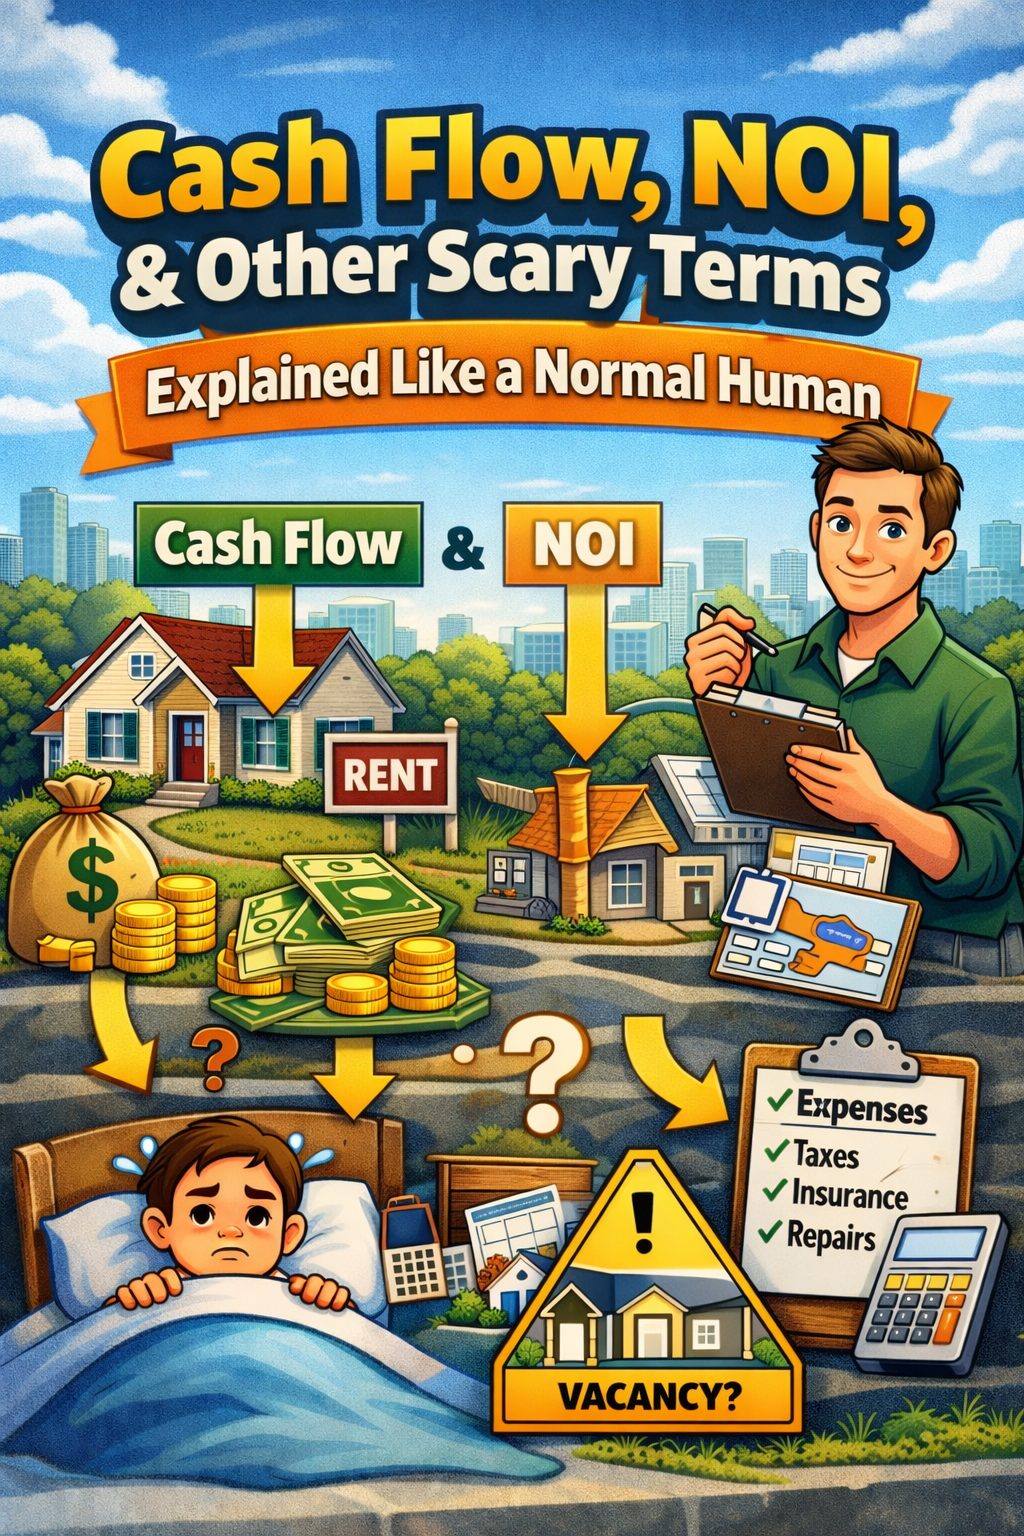
If you’ve ever looked at a real estate post, spreadsheet, or deal breakdown and thought:
“Why does this feel like a math test I didn’t study for?”
You’re not alone.
Real estate folks love throwing around terms like cash flow, NOI, cap rate, and DSCR like everyone just casually learned them in high school. Spoiler alert: we didn’t.
So let’s break these down without MBA jargon, without spreadsheets yelling at you, and without pretending everyone wants to be a full-time landlord.
This is real estate math for normal humans.
First: The Big Picture (Read This First)
Every real estate deal boils down to one simple question:
Does this property make more money than it costs to run?
That’s it.
Everything else is just different ways of measuring that answer.
Cash Flow (The One Everyone Actually Cares About)
Plain English Definition
Cash flow is the money left over after everything is paid.
Think of it like your paycheck:
- Income comes in
- Bills go out
- Whatever’s left is what you actually get to keep
Formula (No Calculator Required)
Cash Flow = Rent – ALL Expenses – Mortgage
Real-Life Example
- Rent collected: $1,800
- Expenses (taxes, insurance, maintenance, etc.): $600
- Mortgage payment: $900
Cash Flow = $300/month
That’s $300 in your pocket every month.
That’s it. That’s the win.
💡 Why Cash Flow Matters
- Pays you monthly
- Helps cover surprise repairs
- Keeps you from feeding the property with your own paycheck
If a property doesn’t cash flow, it better have a really good reason.
NOI (Net Operating Income) – Sounds Scarier Than It Is
NOI is where people usually panic — and they shouldn’t.
Plain English Definition
NOI is how much money the property makes before the mortgage.
Banks love this number. Investors love this number.
It tells everyone how strong the property is on its own.
Formula
NOI = Income – Operating Expenses
🚨 Important:
Mortgage is NOT included.
Example
- Rent: $1,800
- Operating expenses: $600
NOI = $1,200/month
(or $14,400/year)
💡 Why NOI Matters
- Used to value properties
- Used by banks to analyze deals
- Lets you compare deals apples-to-apples
Think of NOI like the property’s engine strength — before financing choices come into play.
Cap Rate (A Comparison Tool, Not a Magic Number)
Cap rate is one of the most misunderstood terms in real estate.
Plain English Definition
Cap rate shows how hard your money is working if you bought the property in cash.
Formula
Cap Rate = NOI ÷ Purchase Price
Example
- Annual NOI: $14,400
- Purchase price: $180,000
Cap Rate = 8%
💡 What Cap Rate Is Good For
- Comparing properties
- Comparing markets
- Sanity-checking asking prices
💡 What Cap Rate Is NOT
- A guarantee of profit
- A promise of cash flow
- A reason to ignore bad numbers
High cap rate ≠ good deal
Low cap rate ≠ bad deal
Context matters.
DSCR (The Bank’s Comfort Blanket)
DSCR sounds terrifying. It’s not.
Plain English Definition
DSCR tells the bank:
“Can this property pay its own mortgage?”
Formula
DSCR = NOI ÷ Annual Debt Payments
Example
- Annual NOI: $14,400
- Annual mortgage payments: $12,000
DSCR = 1.20
💡 What Banks Like
- 1.30+ = Comfortable
- 1.20 = Cutting it close
- 1.00 or Below 1.00 = “We need to talk…”
This protects you and the bank from bad deals.
Operating Expenses (The Silent Killers)
Operating expenses are everything required to keep the property running.
Common Examples:
- Property taxes
- Insurance
- Maintenance & repairs
- Property management
- HOA fees
- Vacancy allowance
🚨 What People Forget
- Maintenance isn’t optional
- Vacancies WILL happen
- Stuff WILL break at the worst time
Underestimating expenses is how “great deals” turn into stress factories.
Putting It All Together (Simple Flow)
1️⃣ Rent comes in
2️⃣ Expenses go out → gives you NOI
3️⃣ Mortgage gets paid → what’s left is Cash Flow
Everything else is just measuring different parts of that flow.
Common Beginner Mistakes (Learn These Early)
❌ Chasing appreciation but ignoring cash flow
❌ Underestimating expenses
❌ Obsessing over cap rate without context
❌ Buying a “deal” that needs constant cash injections
Real estate should support your life, not become your second full-time job (unless that’s the goal).
Final Thought (The Normal Human Rule)
If you can answer these three questions, you’re ahead of most people:
✅ Does it cash flow?
✅ Can it survive a bad year?
✅ Does it fit my risk tolerance and lifestyle?
If yes — congratulations, you actually understand real estate math.
Deal Example: “$200k rental that seems pretty decent”
Purchase price: $200,000
Down payment: 20% ($40,000)
Loan amount: $160,000
Interest rate: 7% (example)
Term: 20 years
Expected rent: $2,000/month
Step 1) Start with income (but be honest)
Gross Scheduled Rent:
$2,000 × 12 = $24,000 / year
Now add a vacancy allowance (because tenants are not immortal).
Vacancy (5%):
$24,000 × 5% = $1,200
✅ Effective Gross Income (EGI):
$24,000 − $1,200 = $22,800
Step 2) List operating expenses (the stuff that ruins “easy money”)
Let’s use common, realistic estimates:
- Property taxes: $2,400/yr
- Insurance: $2,500/yr
- Maintenance reserve: $1,200/yr (yes, you need this)
- CapEx reserve (big stuff): $1,200/yr (roof/HVAC/paint)
- Misc/landlord paid utilities: $0 (assume tenant pays)
✅ Total Operating Expenses:
$2,400 + $2,500 + $1,200 + $1,200 = $7,300/yr
Step 3) Calculate NOI (before mortgage)
NOI = EGI − Operating Expenses
$22,800 − $7,300 = $15,500 NOI / year
That’s the property’s “engine strength.”
Step 4) Add the mortgage and get cash flow (the part you actually feel)
Approx monthly P&I on $160,000 @ 7% for 20 years is about $1,240/month (ballpark).
Annual debt service:
$1,240 × 12 = $14,880/yr
✅ Cash Flow (before income taxes):
NOI $15,500 − Debt $14,880 = $620/yr
That’s $52/month.
Not sexy. Not terrible. Just… thin.
This is where people either:
- lie to themselves, or
- get smarter with strategy.
Step 5) DSCR (bank-friendly sanity check)
DSCR = NOI ÷ Debt Service
$15,500 ÷ $14,880 = 1.04 DSCR
Translation: It barely covers itself.
Most banks like to see ~1.30+ (varies by lender/property type), so this would be a “we need to talk” deal unless:
- rent is under market and can increase soon, or
- you put more down, or
- expenses are legitimately lower (not “I hope so” lower).
Step 6) Cap Rate (cash-buyer comparison)
Cap Rate = NOI ÷ Purchase Price
$15,500 ÷ $200,000 = 7.75% cap
That’s market-dependent. In some places that’s normal. In others it’s low/high.
Step 7) Cash-on-Cash Return (what your cash is actually earning)
Your cash invested isn’t just down payment. It’s also closing costs + initial reserves.
Let’s assume:
- Down payment: $40,000
- Closing costs: $6,000
- Initial reserve fund: $3,000
Total cash in: $49,000
Cash-on-cash = Annual cash flow ÷ Cash invested
$620 ÷ $49,000 = 1.27%
This is why thin cash flow deals feel “meh” unless there’s a clear rent-growth plan.
Step 8) Quick stress test (the “can I sleep at night?” test)
What if vacancy is 8% instead of 5%?
Vacancy becomes: $24,000 × 8% = $1,920
EGI becomes: $22,080
NOI becomes: $22,080 − $7,300 = $14,780
Cash flow becomes: $14,780 − $14,880 = −$100/yr (negative)
So one small change flips it.
This deal is “works if everything goes right.”
That’s not always bad — but you need to know it.
So is this a good deal?
It’s not a bad deal. It’s a thin deal.
When a thin deal becomes solid:
- Rent is under market and you can raise it responsibly
- You can buy cheaper (price reduction)
- You can put more down (improves DSCR/cash flow)
- You self-manage and truly treat reserves responsibly
- It’s a long-term appreciation area and you can float lean years
When a thin deal becomes a headache:
- You’re tight on cash reserves
- You hate surprise repairs
- You’ll panic if it’s vacant 45 days
- You’re counting on “it’ll probably be fine” math
Disclosure:
This content is intended solely for general financial education and discussion. It does not constitute advice, recommendations, or solicitation of any kind. The author is not providing services as a financial advisor, investment advisor, tax advisor, or legal advisor. All views expressed are personal and do not represent the views, policies, or positions of the author’s employer or any affiliated institution. No compensation has been received for this content. Any financial decisions should be made in consultation with appropriately licensed professionals.